Data insight · Nov 18, 2026 · 5 min read
Bitcoin longs lost $1.32 billion in two days, the most in the eight months of data we hold
Futures exchanges force-closed $692 million of bitcoin longs on 13 November and $629 million on 14 November, more in two days than in any pair since our liquidation record began in March. Leverage has drained out since: funding sits near zero, and a petahash earns 10% more BTC than before the selling.
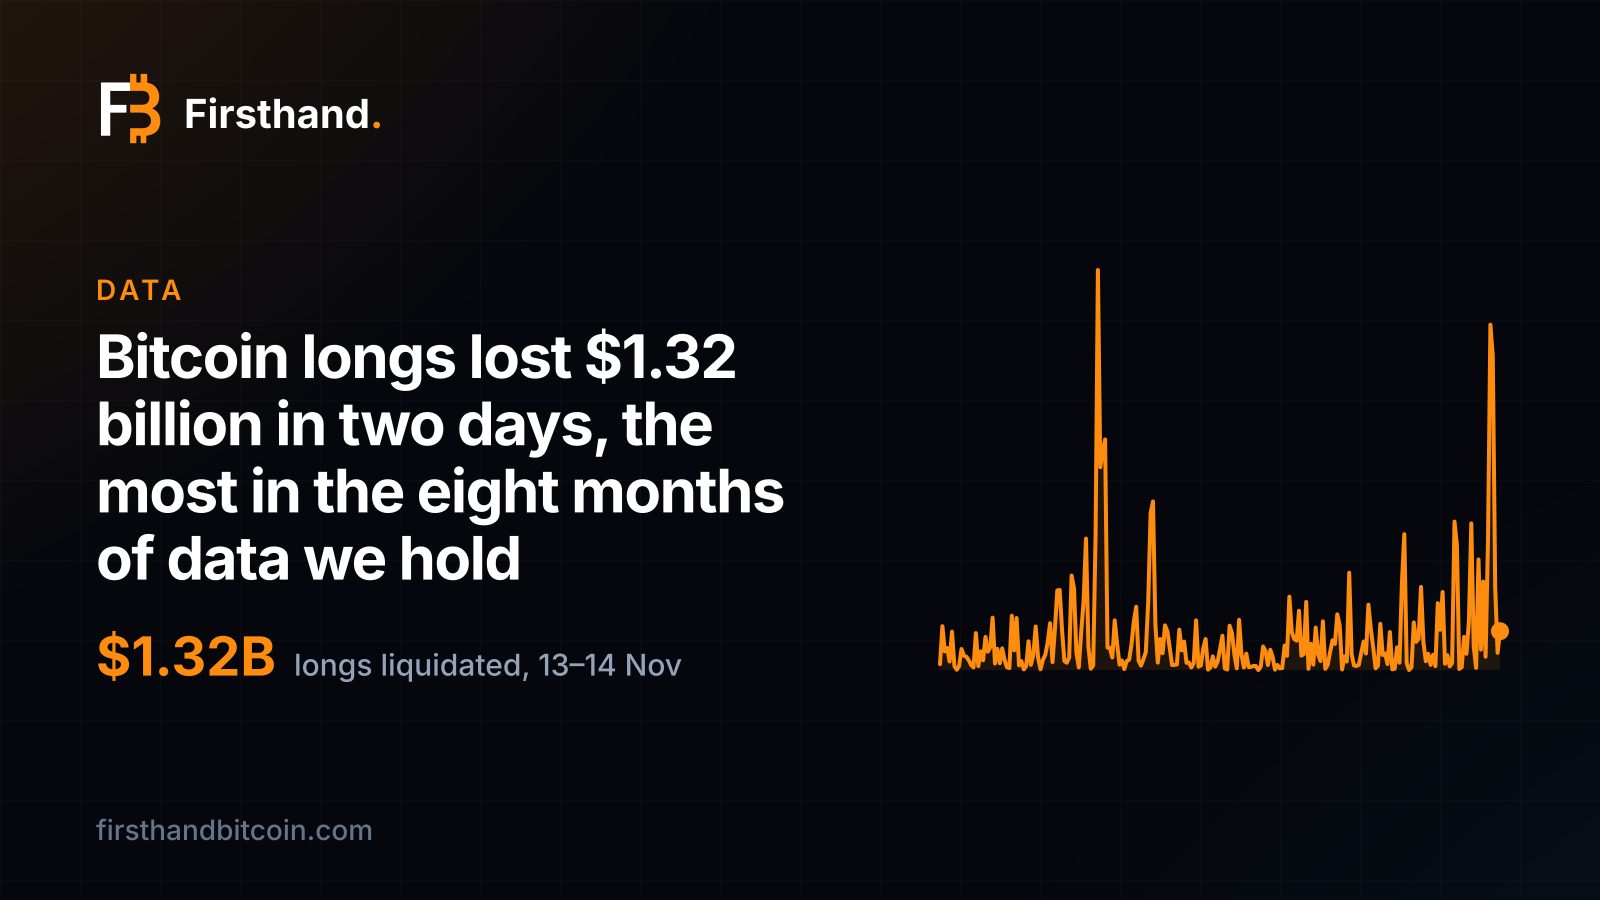
Two days took $1.32 billion of longs
Futures exchanges force-closed $692 million of bitcoin long positions on 13 November and $629 million on 14 November, on our liquidations chart: $1.32 billion in two days. Shorts lost $120 million over the same two days. A long is a bet that the price rises, usually made with borrowed money, and when the price falls far enough the exchange sells it for the trader.
The selling met a falling market. Bitcoin closed at $73,931 on 12 November, $71,366 on 13 November, $68,232 on 14 November and $64,119 on 15 November, on our price chart. A hotter-than-expected US inflation report and rising Treasury yields had lifted the odds of a Fed rate rise, The Motley Fool reported. On Sunday the price touched $62,100, its lowest since 14 July, CoinDesk reported.
October's quieter version of the same pattern is in our October liquidations piece.
It was bigger than the June washout
Our liquidation series starts on 28 March 2026, so it holds a little under eight months. In that time no two days have closed more longs than 13 and 14 November. The nearest pair is 2 and 3 June, at $1.21 billion. The largest single day is still 2 June, at $802 million.
Across the first 17 days of November, $2.88 billion of longs have been force-closed, against $943 million of shorts. That is more than all of October's $2.15 billion and second only to June's $4.17 billion among the full months we hold.
Others measure it over different windows and across the whole crypto market, and arrive at larger totals. The Block counted $1.68 billion of longs closed across the crypto market in the 24 hours to 8 a.m. Eastern on Sunday 15 November, using CoinGlass's hourly data. Decrypt wrote that 13 and 14 November brought "some of the largest long liquidations relative to open interest since 2023".
Seventeen days of November have already cost longs more than all of October.
Half the fall in open interest was positions closing
Open interest, the value of every bitcoin futures position still open, was $32.44 billion on 13 November and $27.37 billion on 17 November on our open interest chart, 15.6% less. Part of that is simply the price: the same positions are worth fewer dollars when bitcoin is cheaper.
Counted in bitcoin, open interest went from 454,543 BTC to 422,205 BTC, 7.1% less. That 7.1% is the leverage that actually left: positions closed by the exchanges or by their owners. The rest of the dollar fall is the price.
In June the same measure fell further. Open interest went from 436,903 BTC on 2 June to 391,827 BTC on 10 June, 10.3% less, as the washout ran over more days. CME, where US institutions trade, held $6.62 billion on 17 November, down from $7.15 billion on 13 November.
Nobody is paying for leverage now
The funding rate on the perpetual contract is what longs pay shorts, every eight hours, to keep their positions open. On our funding chart it ran at an annualised 4.4% on 10 November and 2.5% on 13 November. On 15 November it was 0.03%, and it is 0.03% again this morning.
A rate that close to zero means the traders still in the market are not leaning either way with borrowed money. CoinDesk reported on 16 November that funding had turned negative on the largest exchanges, with shorts paying longs. In June the rate went further, to minus 5.8% annualised on 5 June. It can also swing fast the other way: in September it fell from 21% to below zero in four days after a short squeeze, as our September funding piece shows. Today's reading is a market with very little borrowed money left in it.
What it means for a miner
Every long closed on 13 and 14 November was a holder of bitcoin who had borrowed to hold it, and was sold out by the exchange when the price moved. A miner who pays the power bill from income and keeps what the machine makes has no margin to call: the BTC in the wallet stay there whatever the price does on a given day. That is the model our guide to keeping the BTC sets out.
The same week paid working machines more bitcoin. As the price fell, machines across the network switched off, blocks slowed to 113 on 13 November on our blocks per day chart, and difficulty was cut on 14 November. A petahash earns 0.000469 BTC a day at today's difficulty on our hashprice in bitcoin chart, 10% more than the 0.000427 it earned on 13 November. Our next adjustment page currently estimates a rise of about 10.6% at the next retarget, which would take most of that back.
On the most efficient machine in stock, the Antminer S23 XP Hyd at 8.9 J/TH on Nigeria's 3.9 cents, one BTC costs about $17,800 of electricity at today's hashprice, against about $64,800 to buy on 18 November: 27% of the price.
Output is not guaranteed, and these figures hold today's conditions flat. They depend on bitcoin's price, network difficulty and the machine's uptime.
A long can be sold out from under its owner. A mined BTC cannot.
Sources and further reading
- Bitcoin slips after rebounding from July 14 low that triggered $2 billion of liquidations — CoinDesk, 16 Nov 2026
- CZ denies Binance sold crypto as Bitcoin bounces from four-month low near $62,000 — The Block, 15 Nov 2026
- Bitcoin Investors Are Capitulating—That's Historically Been a Bottom Signal — Decrypt, 17 Nov 2026
- Why Bitcoin is falling today — The Motley Fool, 13 Nov 2026
Disclosure
Firsthand Bitcoin sells and hosts mining hardware, including this machine. No manufacturer, distributor or affiliate programme paid for or reviewed this page and we take no commission on the links above. Historical figures are computed from daily bitcoin price and network hashprice, each day valued at its own prices. Nothing here is investment advice.